For many high-net-worth individuals, the first serious look at alternative assets begins with a simple question: is there something beyond stocks, mutual funds and fixed deposits that can diversify my wealth? In recent years, the answer has increasingly pointed to Alternative Investment Funds. AIF investment India has grown rapidly because investors want access to private equity, venture capital, real estate and structured credit strategies that are not available through traditional products.
But an AIF is not a mutual fund with a higher ticket size. It works differently, carries different risks and rewards patience far more than speed. First-time investors who treat it like a familiar product often make avoidable errors, some of which are expensive and difficult to reverse because of long lock-in periods.
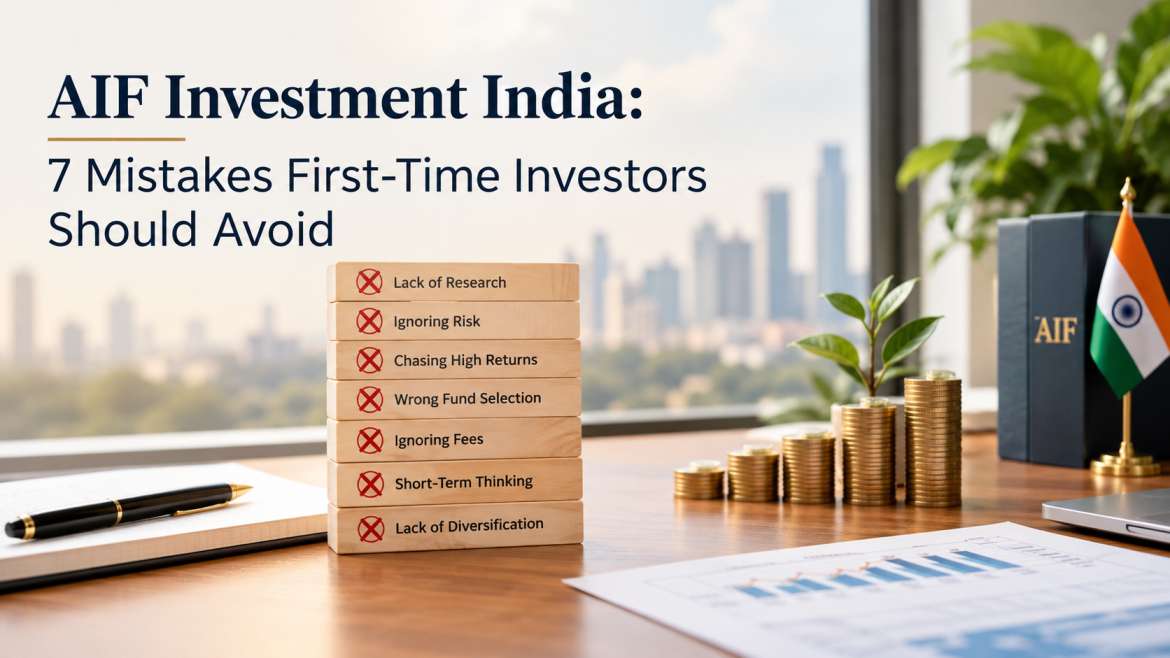
This guide walks through the seven most common mistakes first-time investors make with AIF investment India, and how to avoid each one. Along the way, we also look at how real estate-focused strategies and a well-regarded luxury home investment company can fit into a thoughtful portfolio.
A Quick Primer: What Is an AIF?
An Alternative Investment Fund (AIF) is a privately pooled investment vehicle that collects money from sophisticated investors and invests it according to a defined strategy. In India, AIFs are regulated by SEBI under the SEBI (Alternative Investment Funds) Regulations, 2012. They are divided into three categories:
- Category I AIFs invest in sectors or businesses the government and regulators consider socially or economically desirable, such as start-ups, early-stage ventures, SMEs, infrastructure and social ventures.
- Category II AIFs include private equity funds, real estate funds, debt funds and fund-of-funds. They do not typically use leverage beyond day-to-day operational needs.
- Category III AIFs use diverse or complex trading strategies and may employ leverage, such as hedge funds and long-short strategies.
The minimum investment in most AIFs is ₹1 crore, and the fund is generally open only to investors who meet this threshold and the manager’s own suitability criteria. These are not retail products, and the regulatory design reflects that.
With that foundation, let us look at where first-timers tend to go wrong.
Mistake 1: Not Understanding Which AIF Category You Are Buying
The most basic and most common error is investing without knowing which category the fund belongs to. Many first-time investors hear “AIF” and assume all funds behave alike. They do not.
A Category I venture fund may hold early-stage companies where many investments fail and a few drive returns. A Category II real estate fund may focus on residential or commercial projects with defined project timelines. A Category III fund may trade actively and show far more volatility. Each carries a different risk profile, a different return pattern and a different time horizon.
How to avoid it: Before committing capital, ask the fund manager to explain in plain language what the strategy is, how the fund makes money, what the typical holding period is and what could go wrong. If the explanation is vague or leans on jargon, treat that as a warning sign. A good fund manager welcomes these questions.
For investors drawn to tangible assets, real estate-focused Category II funds are often the natural starting point because the underlying asset class is familiar, even if the fund structure is not.
Mistake 2: Ignoring Lock-In Periods and Liquidity
This is the mistake that causes the most regret. Unlike a mutual fund, where you can usually redeem in a few days, AIFs are built for long holding periods. Under SEBI rules, Category I and Category II AIFs must be close-ended with a minimum tenure of three years. Many funds run five to seven years, with possible extensions.
In practice, this means your capital may be inaccessible for years. There is typically no easy exit, and any secondary sale of units depends on finding a buyer and on the fund’s terms.
How to avoid it:
- Invest only money you will not need for the full fund tenure, plus a buffer for extensions.
- Keep adequate emergency funds and liquid investments outside the AIF.
- Read the exit and extension clauses carefully, including how and when distributions are made.
A useful rule of thumb is to treat AIF capital as long-term, patient capital. If a medical expense, a business need or a property purchase could require this money within three to five years, it probably should not go into an AIF.
Mistake 3: Chasing Past Returns and Headline IRR Numbers
Every fund presentation highlights its best numbers. First-time investors often anchor on a headline IRR (internal rate of return) or a past fund’s performance and assume the next fund will repeat it. That is a risky assumption.
Past performance depends on market cycles, the specific projects or companies held, exit timing and leverage. A strong result in a rising market does not guarantee the same outcome in a flat or falling one. Also, projected or targeted returns are not promised returns. SEBI’s regulations restrict misleading performance claims, and any fund that talks about assured or guaranteed returns should be treated with serious caution.
How to avoid it:
- Look at the whole track record, not just the best fund. Ask about funds that underperformed and why.
- Understand the difference between gross returns and net returns after fees, expenses and carry.
- Ask how returns were calculated and whether they are realized or only on paper (unrealized valuations).
- Compare IRR with the multiple on invested capital (MOIC) to understand both speed and scale of returns.
Sensible AIF investment India decisions rest on understanding how returns are generated, not on the size of a marketing number.
Mistake 4: Skipping the PPM and Misunderstanding the Fee Structure
Every AIF issues a Private Placement Memorandum (PPM), the document that spells out the strategy, risks, fees, governance, valuation method and exit terms. Many first-time investors never read it in full, relying on a presentation or a relationship manager’s summary instead.
The PPM matters because fees can significantly change what you actually earn. Typical AIF costs include:
- Management fee, charged annually on committed or invested capital.
- Performance fee or carried interest, a share of profits above a hurdle rate.
- Setup and administrative costs, charged to the fund.
- Distributor or placement fees, which may or may not be built into the structure.
Small differences in how fees are calculated, for example on committed versus invested capital, can add up over a five- to seven-year period.
How to avoid it:
- Read the PPM fully, or have your lawyer or financial advisor review it.
- Ask for a worked example showing how fees affect net returns.
- Check the hurdle rate, catch-up clause and distribution waterfall.
- Confirm that all costs have been disclosed to you in writing.
If you do not understand a clause, ask. A transparent manager will explain it clearly.
Mistake 5: Not Vetting the Fund Manager, Sponsor and Underlying Assets
An AIF is only as good as the team managing it. First-time investors sometimes choose funds because a friend invested, or because the brand sounds familiar, without doing their own due diligence.
For a real estate-oriented fund, this is especially important. The sponsor’s execution record, the quality of the developers or projects selected and compliance with regulations such as RERA all affect risk. The same logic applies if you are evaluating a luxury home investment company directly: the strength of its track record, land and project selection, approvals, delivery history and financial discipline matter more than polished brochures.
How to avoid it:
- Verify that the fund is registered with SEBI and check the registration details on the SEBI website.
- Research the sponsor and investment manager: years of experience, past fund outcomes, litigation history and governance practices.
- Ask how much the sponsor has invested in the fund itself (skin in the game).
- For real estate strategies, confirm RERA registration of underlying projects, title clarity and status of approvals.
- Talk to existing investors if possible, and ask how communication, reporting and exits have been handled.
A credible luxury home investment company or fund manager will share this information openly. Reluctance to provide it is itself a data point.
Mistake 6: Over-Concentrating Your Portfolio
Enthusiasm is natural when you discover a new asset class. But many first-time investors put too large a share of their net worth into a single AIF, a single strategy or a single sector. Because AIFs are illiquid and long-dated, concentration risk is harder to fix later.
Suppose a significant part of your wealth is already in real estate, whether a business property, a family home or land. Adding a large real estate AIF on top of that could leave you overexposed to one asset class and one economic cycle.
How to avoid it:
- Decide in advance what percentage of your investable surplus will go to alternatives. Many advisors suggest keeping it a modest portion of the overall portfolio.
- Diversify across strategies, vintages and managers over time rather than committing everything at once.
- Consider your existing exposure to the same sector, such as property, before adding more.
- Stagger commitments across years if possible.
A balanced approach to AIF investment India treats the fund as one component of a diversified plan, not as a replacement for the rest of it.
Mistake 7: Overlooking Tax, Documentation and Exit Planning
Taxation of AIFs is more nuanced than for most traditional products. Category I and Category II AIFs generally enjoy pass-through status, meaning income (other than business income) is taxed in the hands of investors rather than at the fund level. Category III funds are typically taxed differently. The nature of income, such as capital gains, interest or dividends, and the holding period can change the tax outcome.
Capital is also called in tranches (drawdowns) rather than invested all at once, and investors must meet commitments on time or face penalties under the contribution agreement.
How to avoid it:
- Speak with a chartered accountant or tax advisor before investing, not after.
- Understand the drawdown schedule and keep funds available to meet capital calls.
- Keep copies of the contribution agreement, PPM, side letters and statements.
- Review how and when distributions will be made, and plan for what you will do with the proceeds.
- Check KYC, FATCA and other compliance requirements early to avoid delays.
Tax rules change from time to time, so always verify the current position with a qualified professional.
Where a Luxury Home Investment Company Fits In
Real estate has long been a favourite asset class for Indian families, and the luxury residential segment has attracted particular interest because of limited supply in prime locations, strong demand among affluent buyers and the potential for appreciation over time. That said, buying luxury property directly requires large capital, specialist knowledge and time, and it can be hard to diversify.
Two routes are common:
- Direct exposure through a luxury home investment company that develops, acquires or manages premium residential properties.
- Pooled exposure through a real estate-focused AIF, which can spread capital across multiple projects under professional management.
Both routes carry risk, including approval delays, market slowdowns, construction risk and liquidity constraints. The right choice depends on your goals, your time horizon and how much involvement you want. Many investors choose to understand both before deciding.
A Simple Checklist for Your First AIF Investment
Before you sign anything, run through this list:
- Do I understand the fund’s category and strategy?
- Can I leave this money untouched for the full tenure plus extensions?
- Have I looked at the full track record, not only the best numbers?
- Have I read the PPM and understood all fees?
- Have I verified the manager’s SEBI registration and track record?
- Is this investment a reasonable share of my total portfolio?
- Have I consulted a tax advisor and understood the drawdown schedule?
If you can answer yes to all seven, you are in a far stronger position than most first-time investors.
Frequently Asked Questions
What is the minimum investment for AIF investment India? The general minimum is ₹1 crore per investor. Some categories, such as angel funds, and certain employees or directors of the manager, may have lower thresholds under SEBI rules.
Are AIFs safe? No investment is risk-free. AIFs are regulated by SEBI, but they can lose value, and returns are not guaranteed. Risk depends on the strategy, manager and market conditions.
How long is the lock-in? Category I and II AIFs must have a minimum tenure of three years, and many run for five to seven years or longer.
Can NRIs invest in AIFs? Yes, NRIs can generally invest, subject to FEMA, KYC and other regulatory requirements. They should confirm the specifics with the fund manager and their advisor.
How is a luxury home investment company different from a real estate AIF? A luxury home investment company typically operates directly in premium residential property, while a real estate AIF pools investor money into a managed portfolio of projects. The risk, liquidity and regulatory frameworks differ, so compare both carefully.
Final Thoughts
AIF investment India offers qualified investors access to opportunities beyond the public markets, but it rewards preparation, patience and discipline. The seven mistakes above, from misunderstanding categories to ignoring tax and exit planning, are all avoidable with a little homework.
Take your time, ask direct questions, read the documents and seek independent advice. Whether you eventually choose a pooled fund or work with a trusted luxury home investment company, a clear understanding of what you are buying is the best protection you have.
Disclaimer: This article is for general information only and is not investment, tax or legal advice. Investments in AIFs are subject to market risks, and past performance is not indicative of future returns. Please read all scheme documents carefully and consult a qualified advisor before investing.